What If Walter Was In Charge Of Our Term Life Insurance
If you’ve spent time here at Peanut Butter and Whine, you may already know Walter, my Bernese/Great Pyrenees mix.
What if Walter was the Chief Family Planning Officer?
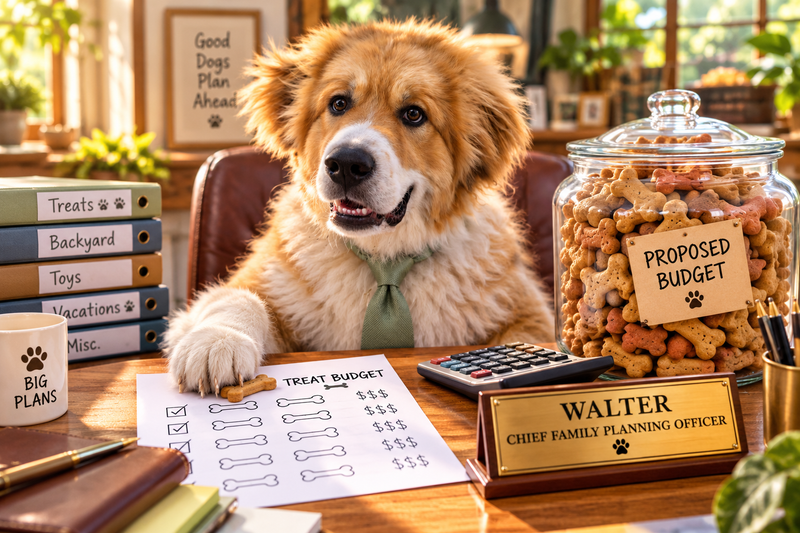
No doubt, you would want to know his qualifications, right? Well, Walter has excellent fluff; it is all over my carpet in big white clumps. He has a commanding presence at 108.8 pounds. He is a momma’s boy. He can roll over, play dead, and he has absolutely no ability to explain a term life insurance for parents.
If you’ve read Walter’s Guide to Puppy Survival, you already know his qualifications include chewing socks and supervising humans. Naturally, I’ve promoted him to financial management.
Has exploring insurance been sitting on your someday list? Walter suggests one place to explore your options.
Walter will be supervising this conversation in an honorary capacity only. Compensation will be discussed in treats.
Walter’s Financial Plan Needs Some Work
Let’s imagine asking Walter to prepare a household budget.
I suspect the proposed categories would look something like this:
- Food.
- Treats.
- More food.
- An emergency reserve of treats.
- Whatever is left for the humans.
A bold proposal. Difficult to get past the mortgage company.
But it raises a useful question: Who depends on us, and what would they need if we were no longer here?
For parents, that question can include children, a partner, and other family members who rely on their income or daily care.
It’s a serious conversation. Having a fluffy imaginary board member makes it a little easier to start.
What Is Term Life Insurance for Parents?
Term life insurance provides coverage for a set period of time. If the insured person dies during that period while the policy is in force, it pays a death benefit to the beneficiaries, subject to the policy’s terms.
That money can help loved ones with expenses such as housing, everyday bills, and caring for children. Walter is sad that it does NOT include fur-babies.
This is life insurance for people. Walter’s veterinary care would fall under a separate pet insurance discussion—and Walter would like that meeting canceled.
The point of term life insurance is to consider the financial support your loved ones might need during a particular stage of life.
You don’t have to understand every insurance term before you begin learning.
Walter understands none of them, and he has already promoted himself to management.
Start With the Bills That Keep Showing Up
Unfortunately, household expenses do not pause politely when a family experiences a loss.
The mortgage or rent still comes due. There are groceries, utilities, transportation costs, and possibly childcare or outstanding debts.
Then there are the longer-term goals, such as education. Walter is happy that this education does not include puppy classes.
Before choosing coverage, consider your family’s expenses, existing savings and insurance, and how long financial support might be needed.
The National Association of Insurance Commissioners’ life insurance resources can help you understand policy types and questions to ask.
There isn’t one coverage amount that fits every household.
I wouldn’t let Walter choose a dog bed without checking the measurements. A financial decision deserves at least that much attention.
Remember the Work That Doesn’t Come With a Paycheck
A household also runs on work that never appears on a pay stub.
Childcare. Cooking. School pickups. Appointment scheduling. Remembering that tomorrow is the day someone needs a clean shirt of a very specific color.
If the person doing that work died, the family might need to pay for help or adjust working hours.
Those responsibilities belong in the planning conversation, too.
For this meeting, Walter has volunteered to oversee morale.
It’s an important position. It does very little laundry.
An Emergency Fund Has a Different Job
Life insurance and emergency savings serve different purposes.
An emergency fund is money set aside for unexpected expenses, such as a car repair, a broken appliance, or a loss of income.
The Consumer Financial Protection Bureau’s guide to building an emergency fund offers practical ways to get started.
You can begin with a manageable savings goal based on your circumstances.
Walter’s imaginary contribution is a tennis ball and an optimistic expression. Appreciated, but unlikely to cover a replacement water heater.
Make Sure Someone Can Find the Important Stuff
A plan is much more useful when the right person knows where to find it.
Keep important records securely organized, including insurance details and household contacts. Make sure a trusted person knows how to access the information they would need.
“Somewhere in that drawer” is a challenging filing system.
Especially when that drawer also contains mystery keys, old batteries, and enough charging cables to support a small telecommunications company.
While you’re organizing, Ready.gov’s family emergency planning guide can help you think through communication and your household’s needs.
For families with pets, include their care instructions and a person who could help. (YES, Walter’s ears perked up!)
Walter may be our honorary planning officer, but a plan that requires him to operate a phone has a significant design flaw.
Questions to Ask Before Choosing Term Life Insurance
Before deciding on a policy, ask:
- How much financial support would my loved ones need?
- How long would they need that support?
- What coverage and savings do we already have?
- What premium can we comfortably maintain?
- What exclusions and conditions apply?
- What happens when the term ends?
- Who should be named as beneficiaries?
Read the details and ask questions when something is unclear. Pricing, eligibility, and availability can vary.
You are allowed to ask someone to explain a sentence again.
Walter and I support this approach. Although his preferred explanation would probably involve a biscuit demonstration.
Walter’s Meeting Could Have Been an Email
Planning for your family doesn’t require finishing everything in one afternoon.
Start by reviewing your household expenses. Find out what coverage you already have. Write down the questions you want answered.
Then take the next step that fits your circumstances.
You can love your family, laugh at your dog, and still make room for a serious conversation about their future.
As for Walter, his appointment as Chief Family Planning Officer remains honorary.
The position comes with no signing authority.
I’ve seen the proposed treat budget.


One Comment
Terri Quick
Too funny lol